THEBUSINESSBYTES
BUREAU
NEW
DELHI, SEPTEMBER 21, 2026
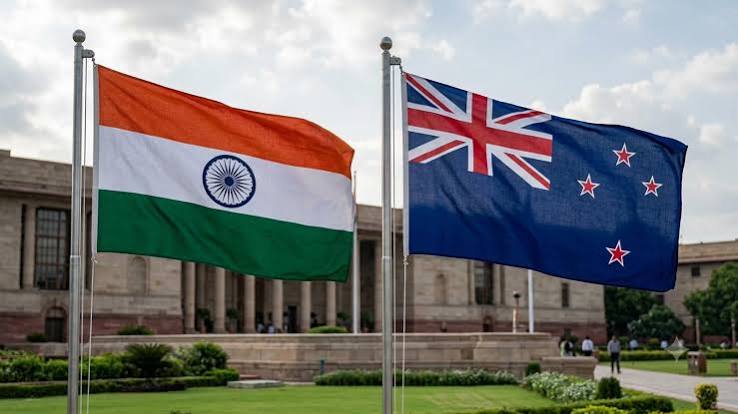
India and New Zealand
are set to usher in a new era of economic cooperation with the India–New
Zealand Free Trade Agreement (FTA) coming into force on October 20, 2026,
opening a wider window of opportunities for exporters, investors, businesses
and skilled professionals in both countries.
Union Minister of
Commerce and Industry Piyush Goyal and New Zealand’s Minister for Trade and
Investment Todd McClay announced the implementation date during a virtual
meeting on Monday, following the completion of the required internal processes
in both countries. The New Zealand Parliament passed the legislation on
September 16, 2026.
The landmark
agreement was signed on April 27, 2026, at Bharat Mandapam in New Delhi by
Goyal and McClay.
A key feature of the
pact is New Zealand’s commitment to eliminate duties on every tariff line
covering 100% of India’s exports from the date of implementation. The move is
expected to strengthen the competitiveness of Indian exporters by putting them
on a level playing field with exporters from New Zealand’s other trading
partners.
Major Indian sectors
expected to benefit include textiles and apparel, leather and footwear, gems
and jewellery, engineering goods and processed foods. New Zealand’s peak
tariffs of up to 10% on these products will be eliminated.
Indian manufacturers
will also gain tariff-free access to important industrial inputs, including
wooden logs, coking coal and metal scrap, potentially helping reduce input
costs and improve competitiveness in international markets.
While expanding
market access, the agreement retains safeguards for sensitive Indian
agricultural sectors. Dairy, animal meat except sheep, key agricultural
commodities, sugar and edible oils have been excluded from tariff concessions.
Market access for New
Zealand products such as apples, kiwifruit and Manuka honey will be regulated
through tariff-rate quotas, minimum import prices and seasonal import windows,
alongside safeguard mechanisms for domestic farmers.
The FTA also
establishes an Agriculture Productivity Partnership, supported by dedicated
action plans for kiwifruit, apples and honey. The partnership will promote
knowledge-sharing, technology transfer and capacity building in areas such as
orchard management, post-harvest practices, supply chains, food safety and
sustainable beekeeping.
Centres of Excellence
and a Joint Agriculture Productivity Council will further support
implementation and monitor cooperation initiatives.
Beyond trade in
goods, the agreement is expected to deepen investment ties. New Zealand has
committed to facilitate USD 20 billion in investment into India, with potential
investment opportunities spanning agriculture, manufacturing, infrastructure
and start-ups.
The pact comes as India
and New Zealand seek to build a broader economic relationship under their newly
announced Strategic Partnership and the India–New Zealand Strategic
Partnership: Roadmap to 2030.
The roadmap sets an
aspirational goal of doubling bilateral two-way trade in goods and services to
NZ$7 billion, approximately ₹35,000
crore, by 2030.
The FTA is expected
to serve as a key mechanism for translating those ambitions into commercial
outcomes.
India’s rapidly
expanding services industry will also receive greater access to the New Zealand
market across roughly 118 sectors, including IT, professional services,
audio-visual services, construction and tourism.
The agreement
provides Most-Favoured Nation treatment across about 139 sub-sectors, while
creating new mobility opportunities for Indian professionals and young people.
These include a
dedicated quota of 5,000 Temporary Employment Entry visas for skilled Indians
and 1,000 Working Holiday visas annually for young Indians.
The agreement also
provides uncapped student mobility, with post-study work rights of up to three
years for STEM graduates and four years for doctoral scholars.
Indian pharmaceutical
and medical device companies are also expected to benefit from provisions
designed to streamline regulatory processes.
New Zealand will
accept inspection approvals from globally recognised regulators, including the
US Food and Drug Administration, European Medicines Agency, UK Medicines and
Healthcare products Regulatory Agency, and Health Canada. The move is expected
to reduce regulatory delays and accelerate market entry for eligible Indian
exporters.
Highlighting the
significance of the agreement, Commerce and Industry Minister Piyush Goyal said
the FTA would provide “fresh momentum” to the bilateral partnership, create
greater synergies between the two economies and contribute to overall competitiveness.
The October 20
implementation date also carries symbolic significance, as it coincides with
Dussehra – Vijay Dashami.
Goyal expressed
confidence that the agreement would help overcome barriers to stronger trade,
technology and investment ties while contributing to prosperity on both sides.
New Zealand Trade and
Investment Minister Todd McClay said that at a time of uncertainty in global
trade and rising tariffs, the India–New Zealand FTA would provide greater
confidence to businesses. He described it as one of the highest-quality
agreements concluded by the two countries in nine months and said it would
deliver tangible benefits to businesses and stakeholders.
McClay also
emphasised opportunities for expanded cooperation in people-to-people relations,
culture, sports, business and investment, while noting the importance of
addressing challenges faced by businesses to support employment generation.
The implementation of
the FTA comes as merchandise trade between India and New Zealand stands at
around USD 1.1 billion in 2025–26.
With broad tariff elimination, enhanced services access, investment commitments and new cooperation mechanisms, the agreement marks a significant expansion of the economic framework between the two countries.
For India, the pact places farmers, women, youth, artisans and MSMEs at the centre of a wider trade and investment strategy, while giving Indian businesses greater access to a developed-market economy.